Home/ Income Tax/ Article
Eight ITR filing mistakes that trigger a notice — and how to avoid each one
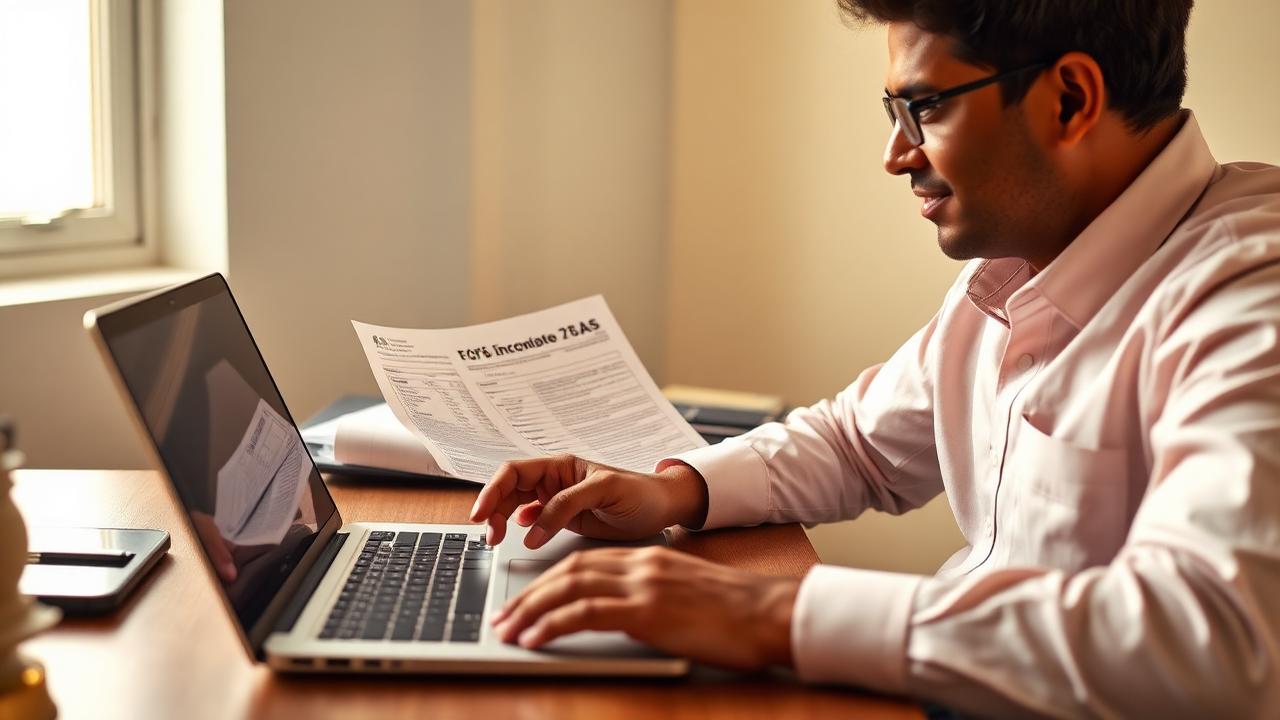
Almost every scrutiny notice we see starts the same way: the return says one thing and the Annual Information Statement says another. Here is what the department already knows about you, and how to file so the two agree.
The department no longer waits for you to disclose income. Banks, mutual fund registrars, depositories, property registrars and employers all report to it, and the totals land in your Annual Information Statement (AIS) long before you open the filing utility. Filing well now means matching a record that already exists, not building one from scratch.
This guide walks through the eight mismatches behind most notices, in the order they usually appear, with the fix for each.
Start from the AIS, not from your bank passbook #
Download the AIS and the Taxpayer Information Summary from the e-filing portal before you enter a single figure. The AIS lists interest credited by each bank, dividends by each company, securities transactions reported by the depository, property purchases above the reporting threshold, and high-value cash deposits.
Read it as a draft of your return prepared by somebody who can only see part of your life. It will contain entries that are wrong — a fixed deposit reported twice, a joint account attributed wholly to you, a sale reported at stamp duty value. Every one of those needs either a correction in your return or feedback submitted against the AIS entry. What it must never get is silence.
- Submit feedback on incorrect entries: information is duplicate, relates to another person, or is not fully correct.
- Keep the acknowledgement. If a notice follows two years later, that acknowledgement is your first line of reply.
- Re-download the AIS a week before filing. It is updated as reporters revise their statements.
Savings and fixed deposit interest that never reached the return #
This is the single most common mismatch. Savings bank interest is often ignored because no TDS was deducted, and fixed deposit interest is reported on receipt while the bank reports it on accrual.
Declare the full interest as income, then claim the deduction separately. Section 80TTA allows up to Rs 10,000 of savings interest for individuals under 60 under the old regime; Section 80TTB allows up to Rs 50,000 of interest, including deposits, for senior citizens. Netting the deduction off before disclosure produces a figure that will never match the AIS.
For deposits running across financial years, use the accrual figures in the bank interest certificate rather than the credit shown in the passbook, and be consistent about it year after year.
TDS claimed in the wrong year #
TDS credit is allowed in the year the corresponding income is offered to tax. Claim the credit in one year and disclose the income in another and the system will flag it automatically at processing under Section 143(1).
| Situation | Where it goes wrong | Fix |
|---|---|---|
| Advance professional fee received in March, invoiced in April | TDS in one year, income in the next | Carry the TDS forward in the TDS schedule and claim it against the year the income is offered |
| Deposit interest accrued but not credited | Income disclosed, TDS not yet reflected | Match to Form 26AS quarter by quarter before filing |
| Employer changed mid-year | Only the second Form 16 used | Combine both, recompute the exemption limits once, not twice |
House property income that was rounded off #
Rental income is not the amount that hit the bank. It is the annual value, less municipal taxes actually paid during the year, less the standard deduction of 30 per cent, less interest on a housing loan within the applicable limit.
Two details create most of the disputes. First, a self-occupied property allows housing loan interest only up to Rs 2 lakh, and the loss set off against other heads is capped at Rs 2 lakh in a year, with the balance carried forward for eight years. Second, if the property was vacant for part of the year, say so; do not silently reduce the rent.
Capital gains taken straight from the broker statement #
A broker profit-and-loss report is prepared for you, not for the department. It usually ignores grandfathering on pre-2018 equity holdings, mixes intraday and delivery trades, and treats a fund switch as if it were not a redemption.
Rebuild the schedule from the capital gains statement issued by the registrar for mutual funds and the contract notes for shares. Every switch, every systematic transfer and every dividend reinvestment is a transaction with its own holding period.
Choosing a regime without doing the arithmetic #
The new regime is the default. Staying in the old regime is a choice you make, and for a salaried person it has to be made every year at the time of filing. Compare on the deductions you genuinely claim — not the ones you intend to start claiming — and remember that the old regime only wins once your verified deductions cross the break-even for your income slab.
Business and professional income is treated differently: opting out of the new regime is filed through the prescribed form and switching back and forth is restricted. Get that decision right the first time.
Foreign assets and ESOPs left undisclosed #
If you hold shares in a foreign parent company, a foreign bank account, or units in an overseas fund, Schedule FA applies even when the holding produced no income and even when the amount is small. Non-disclosure here carries penalties under the black money legislation that are entirely disproportionate to the value involved.
ESOPs of a foreign parent need two entries: the perquisite value at exercise, already in your Form 16, and the holding itself in Schedule FA for the relevant calendar year.
Filing correctly and then not verifying #
An unverified return is not a return. Verify through Aadhaar OTP, net banking or a signed ITR-V within the prescribed window, then check the processing status a few weeks later rather than assuming silence means acceptance.
If an intimation under Section 143(1) shows a difference, respond inside the portal within the time allowed. Most of those differences are arithmetic or credit-matching issues that close in one reply — as long as somebody actually replies.
A pre-filing checklist you can print #
Run through this before you submit. If any line is unticked, you are guessing.
- AIS and Form 26AS downloaded this week and compared line by line
- Feedback submitted on every incorrect AIS entry, acknowledgement saved
- Interest certificates collected from every bank, including dormant accounts
- Capital gains statements from every registrar and broker, switches included
- Both Form 16s combined if you changed employers
- Rent receipts, municipal tax challans and the loan interest certificate on file
- Regime comparison run on actual, claimable deductions
- Schedule FA completed for every foreign holding
- Return verified and the intimation checked after processing
Read next
 Income Tax
Form 16, read line by line
Most people glance at the net figure and file. The three boxes worth actually checking are elsewhere, and two of…
 Income Tax
Old regime vs new regime: how to actually decide
The break-even depends on how much you genuinely claim, not on what you could claim.